


Confessions of a Serial Entrepreneur – Requests of Proposals (RFP’s) and AI
As an entrepreneur I know just enough information when it comes to investing to make me dangerous. It is not that I am not smart enough to understand investments, it is just I do not have the time required to do it myself. This problem has plagued me my whole life. Get excited by a company and purchase it near the top of its crescendo. Then I do not pay attention to it, go back a few weeks later and I have lost money. I have done this with junior mining companies, technology companies, and the list goes on. There has been no end to my stupidity when it comes to investing. So, if you are young and starting to invest here is all the stuff I have learned the hard way. They say the best way to learn is through somebody else’s mistakes but the fastest way to learn is through your own. So here are my mistakes.
Warren Buffet said, “If you aren’t willing to own a stock for ten years, don’t even think about owning it for ten minutes.” Man, I wish I would have known about Warren Buffet in my early days. I bought a lot of junk because I thought I could play the market and create quick gains. It rarely worked and the losses outweighed the gains. And losses make the decision harder as you either sit and wait it out or you sell and get out. If the company is not a solid company, then the sit and wait option costs money because that money could have been invested somewhere else earning better returns.
I started investing after university once I had a full-time job and had paid off my student debt. I read a book called the Wealthy Barber and followed the author’s advice, trying to invest 10% of my income through RRSP’s. I invested in mutual funds mostly as they were diversified and this is what it instructed me to do. The book also suggested investing in real estate, but I had no time to manage properties. The thing I dislike about mutual funds is that a certain percentage goes to the fund managers regardless of performance and that 1-2% premium you pay annually can add up to a lot over your life. I think Wealthsimple gained traction because of their reduced rates and fees. So, I decided that I could save on those fees by doing it alone.
I was born in a period of incredible growth for many companies. I was at Canadore College when they rolled out Microsoft Windows and I knew it was a game changer but did I invest? NO. I did however invest in Palm Pilot when people started showing up to meetings with them. With technology, especially early on it was risky trying to pick the winners. Netscape owned the browser space but then disappeared as Microsoft muscled them out. Google took over Yahoo for search engines and then muscled Microsoft out of the browser business. But then there was a time when the leaders where established and I thought how much more can they grow? They already own the markets – boy was I wrong. All through this period my wife keeps telling me to put our money in the Canadian banks. I put some but not all – hindsight is 20/20 but I should have listened to her. (This is not the first time – but I digress.)
When we were developing Aegis, (our underground mine drill and blast planning software) we were thinking about using statistical models to run our blasting model to predict breakage and the standard deviation of our muck pile (the ore chucks that result from the blast). Troy suggested we use Nvidia chips for processing as they handled math calculations the fastest. At the time they were used in gaming machines. I knew about AI but I did not know that AI would one day run on these chips. But there I am in the middle of it and thinking about using the chips for a similar purpose to that of AI and I did not see it. I did not see it as I was trying to solve a problem we had while not understanding it as an investment opportunity. Our blast optimizations would take a week of compute time to processes using normal chips. We ended up not using them as it would have been too much to ask a mine to upgrade their hardware to run our software. We thought that would limit our sales and we were right at the time. We then focused on using the laws of physics to build our own break model. When you are looking at some technology through one lens you have a myopic viewpoint. This is true of all investments.
One thing about being an entrepreneur is that we face so much risk day to day running a company that we want less risk when we invest. However, at the time the return on bonds was minimal and stocks seemed too risky. A friend of mine introduced us to the potential to invest through a life insurance policy. Basically, at the time it was one of the ways left to move money out of a company paying minimal taxes. Neither Gina nor I had heard about this before, so we were a little skeptical at the time. But the more we investigated it, the better we liked it. The insurance fund invests in only long term 20-year bonds, making it one of the safest investments on the planet. This is basically how we set ourselves up for retirement. I always joke I am worth more dead than alive. This is by far the best investment I have made, because it has set me up for the long run and provided me with less sleepless nights. If anything, I have said in this paragraph makes sense for you, let me know and I will connect you, but you need a business with excess cash in it for it to make sense. No, I was not asked to write this.
I followed the Lazy Investor for a while and practiced his methodology of buying good dividend companies with great track records. I bought stock in the following companies in:
| Company | Purchase Price | Selling Price | Current Price |
|---|---|---|---|
| Coca Cola | $30.18 | $42.65 | $96.68 |
| Abbott Laboratories | $38.43 | $37.46 | $110.46 |
| Becton Dickinson & Co | $79.27 | $132.83 | $277.68 |
| Berkshire Hathaway | $81.67 | $127.50 | $583.34 |
| Visa | $18.14 | $67.77 | $423.00 |
Now my portfolio included more companies then just the ones above. This is just a snapshot. I had to stop as it is a really painful experience to see how much I left on the table. Yes I made some money but if I just followed the Lazy Investor or Warren Buffet, I would still own these stocks. I sold them all on Feb 6, 2016, just after Donald Trump became President. I just saw him as a risk to the American economy and sold. If there is anything that keeps me up a night it is this loss of opportunity. Not to mention that I purchased most of these stock with the dollar was close to par. For instance, I had 580 shares in Visa and purchased those shares when the Canadian dollar was on par with the America dollar. This stock would be worth $343,476 CDN today – ouch. Coulda, woulda, shoulda.
So, what have I learned, if I was to do it all over again? I would invest for the long term. I recently heard an investor say that an undervalued company will sooner or later be recognized for its value by the market, so buy and hold.
So here are my thoughts if I was to do it again (Please seek professional advice for your own portfolio):
- Frist off invest in yourself. More education, more certifications will increase your earning potential. Constantly be learning and improve yourself. It is the least risky investment you can make.
- Start early and invest 10% of your income monthly. Have it come out automatically on payday so you do not notice it. This allows for dollar cost averaging, meaning sometimes you purchase when the market is low and sometimes when it is high. Overall, you are buying shares at prices somewhere in the middle which is okay.
- Do not invest trying to win in the short term. If you do you are gambling. Invest only in companies that you are willing to hold for the long term. Look for companies that have paid dividends over the long term and see how many consecutive years their dividends have grown. You don’t need to invest in just dividend paying companies, but if a company grows its dividends 2% per year then 20 years later you are earning 48.59% per year on your original investment. That is the power of time.
- Diversify your portfolio.
- For Canadians – fill up your Tax-Free Savings Account first, then RRSP, and take advantage of RESP for your kids’ education.
- For any companies that pay dividends – DRIP (dividend reinvestment investment program) all the dividends – meaning that your dividends automatically purchase more shares in the company.
- If you do not have time for all of this look for someone who knows what they are doing to help you. Do a reference check on your investment partner.
- There are less risky investments, such as segregated funds, that reduce the risk because they guaranteed your original investment but do not guarantee gains. These are good to have as part of your overall strategy and later in life they will become even more important when you cannot afford losses.
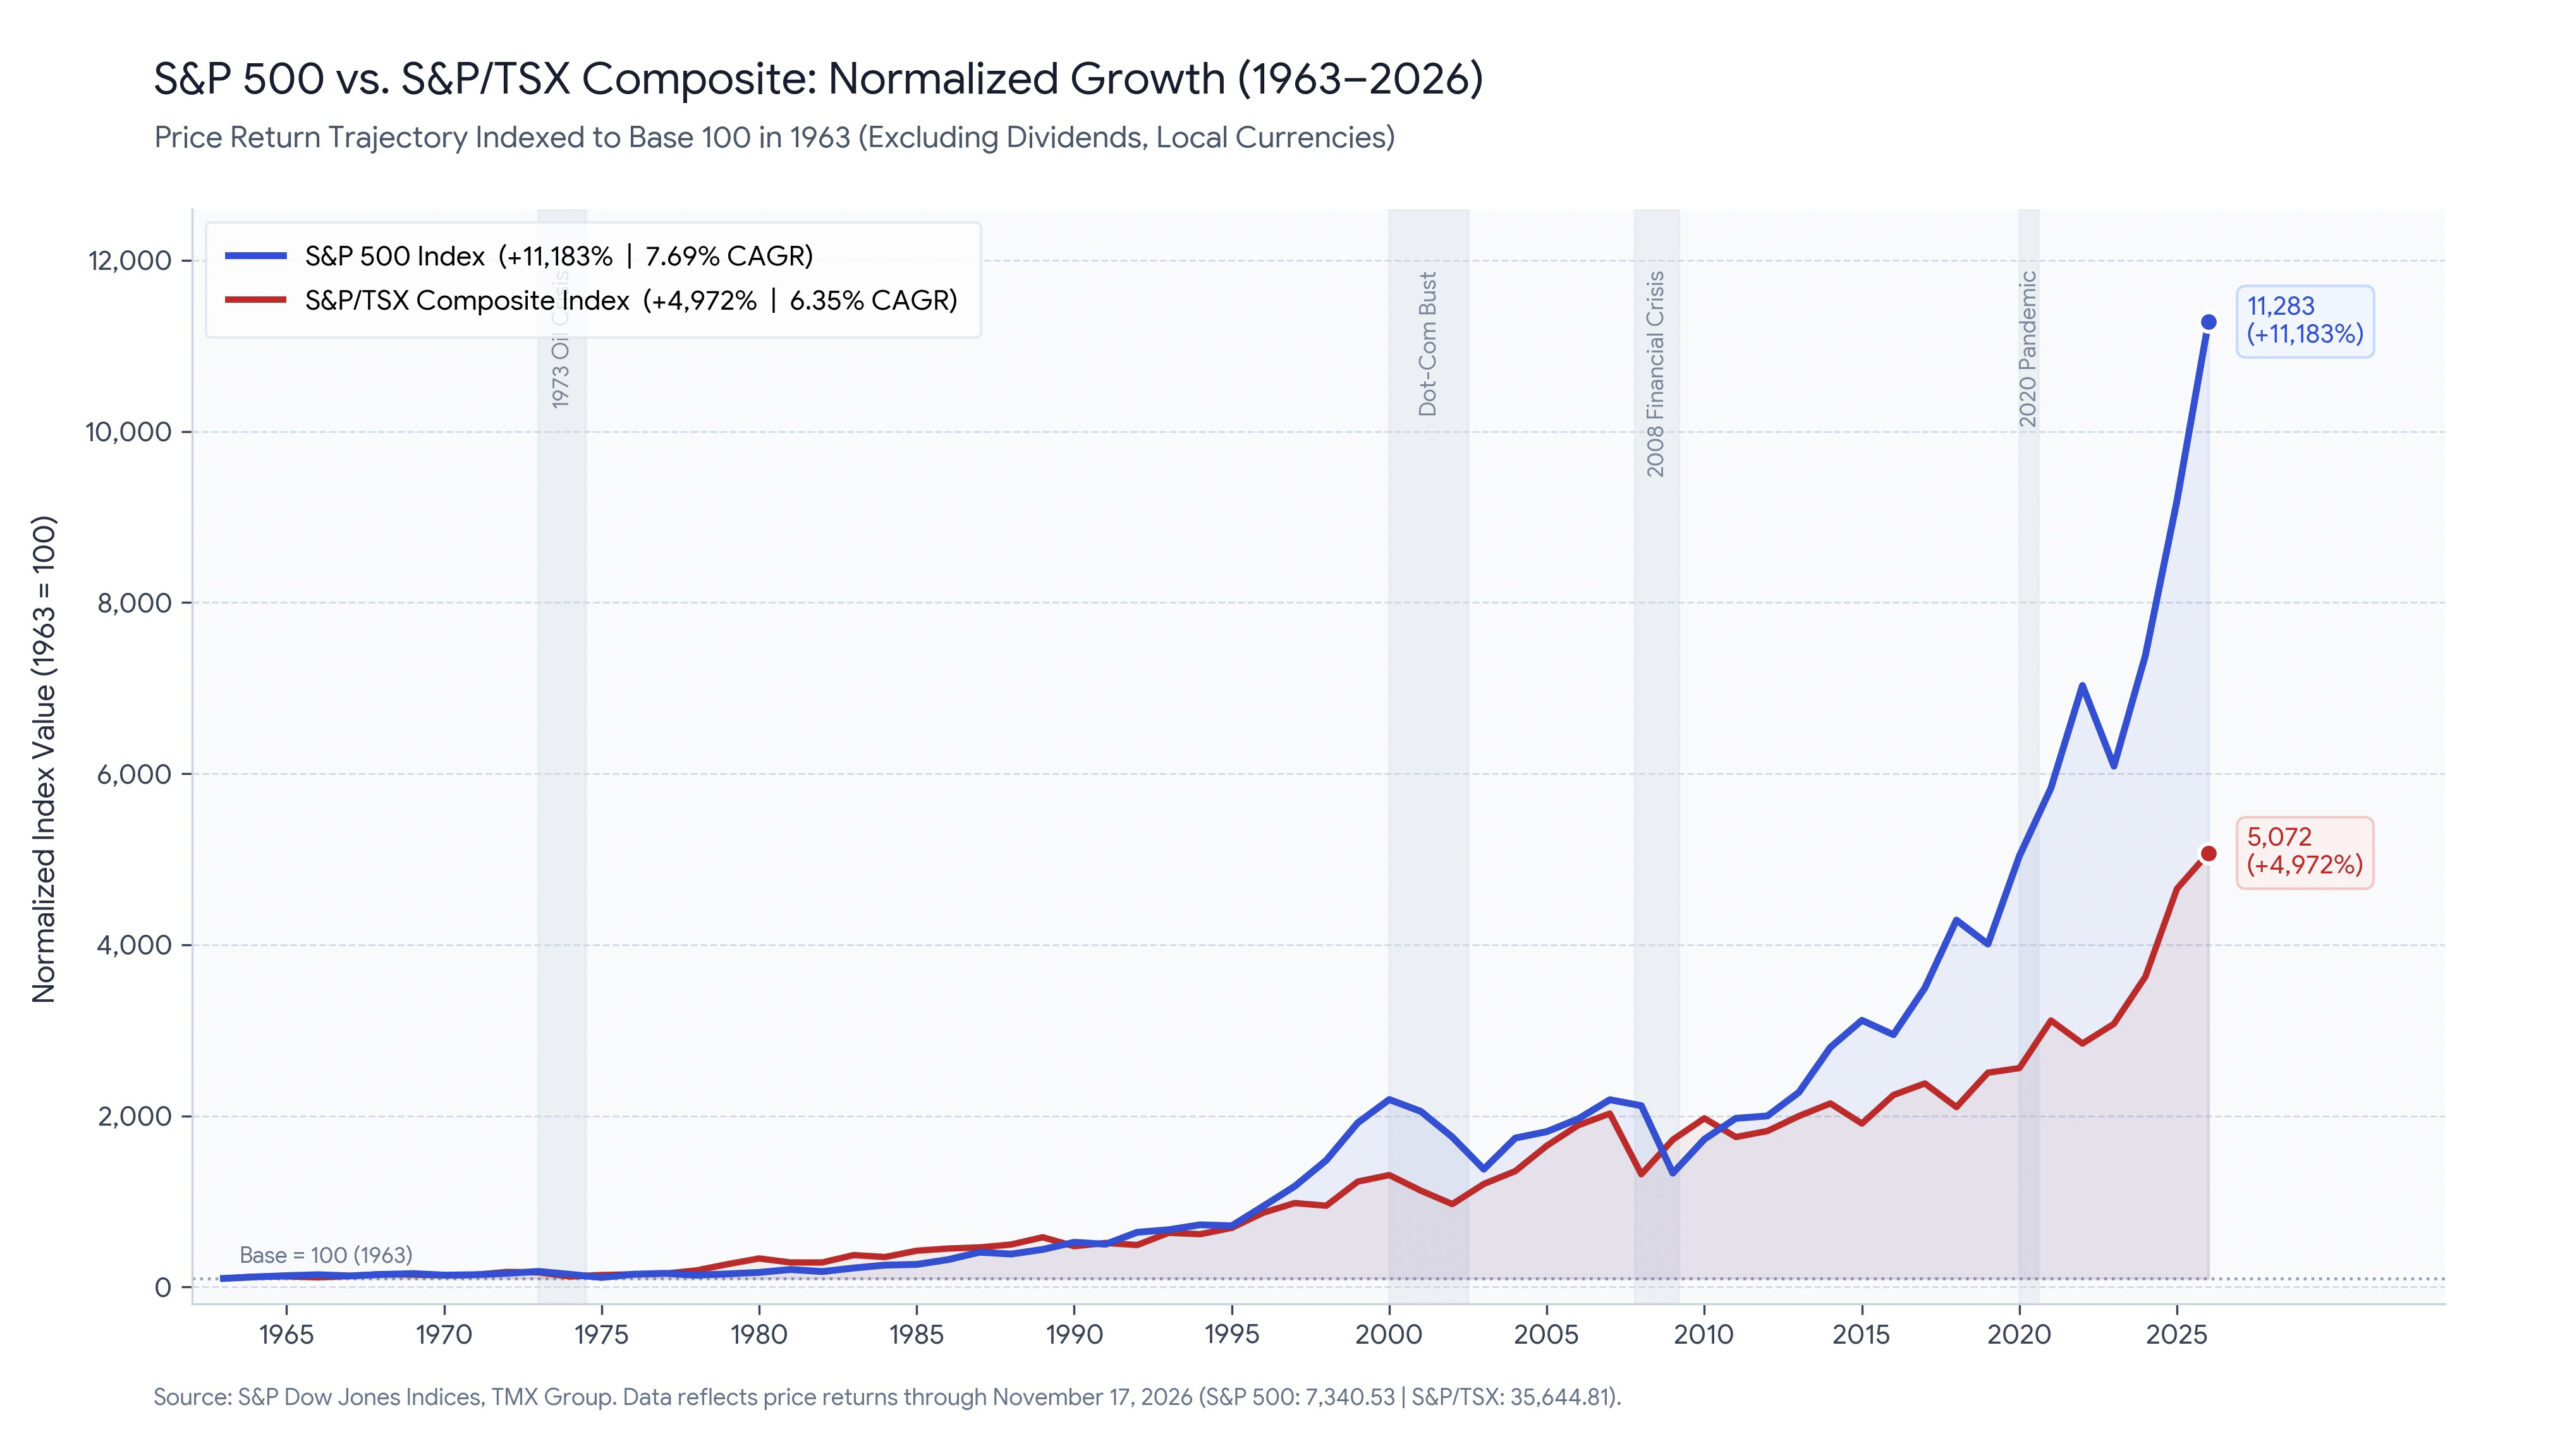
- US stock markets have always outperformed Canadian ones in the long term. Find some ETF or fund that track the S&P 500 and invest in those.
- And of course, listen to Gina and invest in the Canadian banks.
This has been therapeutic. Remember you only need enough money to make it to the end.
“One day, everything you own will either be donated, sold, or thrown away. What will remain is the difference you made in the lives of others.” Anthony Hopkins